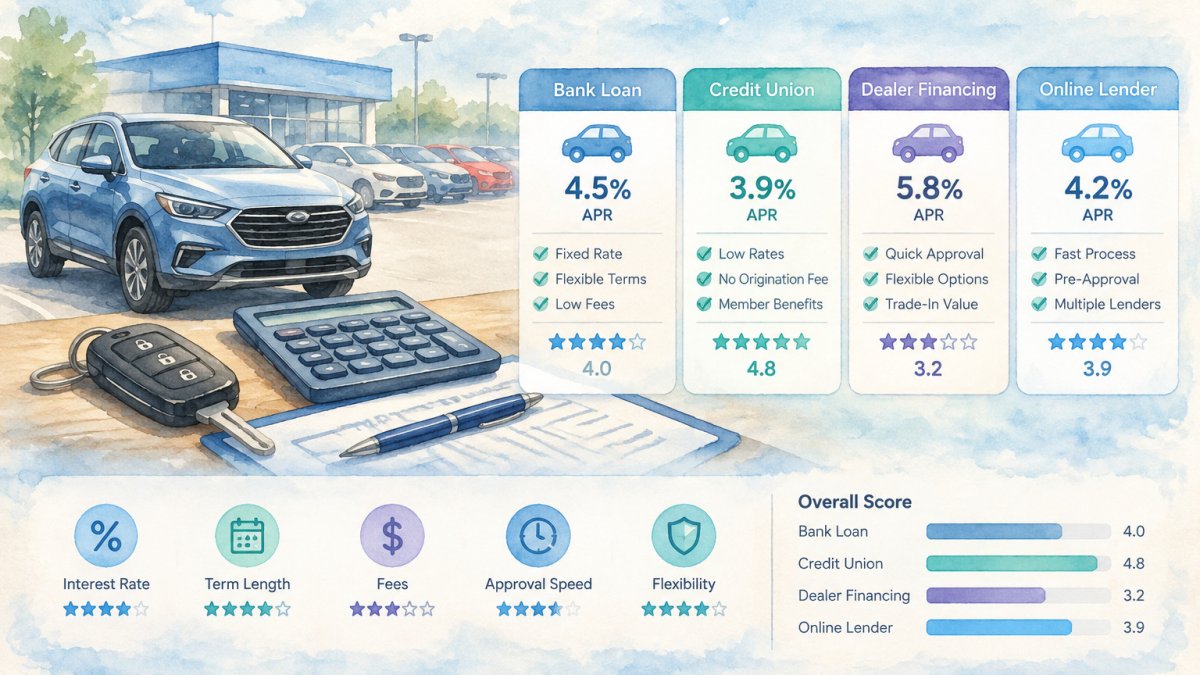
 comparison
Affordable Auto Financing Tools Compared for 2026
Last Updated: November 6, 2026
Quick Summary
Auto financing tools estimate what a car loan could cost before you apply, using the vehicle price, down payment, loan term and an estimated rate to project a monthly payment and total interest. Estimate-only calculators are private but depend on the rate you enter, while offer-comparison marketplaces may return prequalified offers.
- Enter the actual negotiated vehicle price, not the sticker price, plus your down payment and trade-in value.
- Compare offers on total of payments, not just the monthly payment, since longer terms raise total interest.
- Check whether the tool includes fees, taxes and add-ons, since these change the amount financed.
- Estimate-only tools usually need no personal data, while marketplace tools do, so know which you are using.
Table of Contents
- How Auto Financing Tools Work and What They Can Tell You
- Car Loan Calculator Options for Estimating Monthly Payments
- Auto Loan Comparison Calculator Tools Side by Side
- Affordable Auto Financing Tools for Bad Credit Borrowers
- Total Cost, Loan Terms and Fine Print to Check
- Best Used Auto Loans and How to Compare Offers
- Apply Online and Compare Your Financing Options With Silverton Motors
- Frequently Asked Questions
How Auto Financing Tools Work and What They Can Tell You
Auto financing tools estimate what a car loan could cost before you apply. Most use the vehicle price, down payment, loan term and an estimated rate to project a monthly payment and total interest. Used cars and new cars are both financed this way, though used-car rates often run higher than new-car rates.
At Silverton Motors, we want you to walk into financing with clear numbers. A tool gives you a starting point, not a final offer. The estimate is only as good as the inputs you feed it, so treat it as a way to compare scenarios.
Consumer Financial Protection Bureau guide to auto loans
Car Loan Calculator Options for Estimating Monthly Payments
A car loan calculator is the simplest financing tool. You enter the loan amount, interest rate and repayment period, and it returns a monthly payment. A basic car loan calculator is useful for a quick check, but it rarely shows the full picture.
The main limitation is the rate. Most calculators let you type in any number, so a rate that looks reasonable may not match what a lender will offer you. Run the numbers at two or three rates to see how sensitive the payment is.
- Enter the actual vehicle price, not the sticker price before negotiation.
- Include your down payment and any trade-in value.
- Test a shorter term and a longer term, then compare total interest.
Auto Loan Comparison Calculator Tools Side by Side
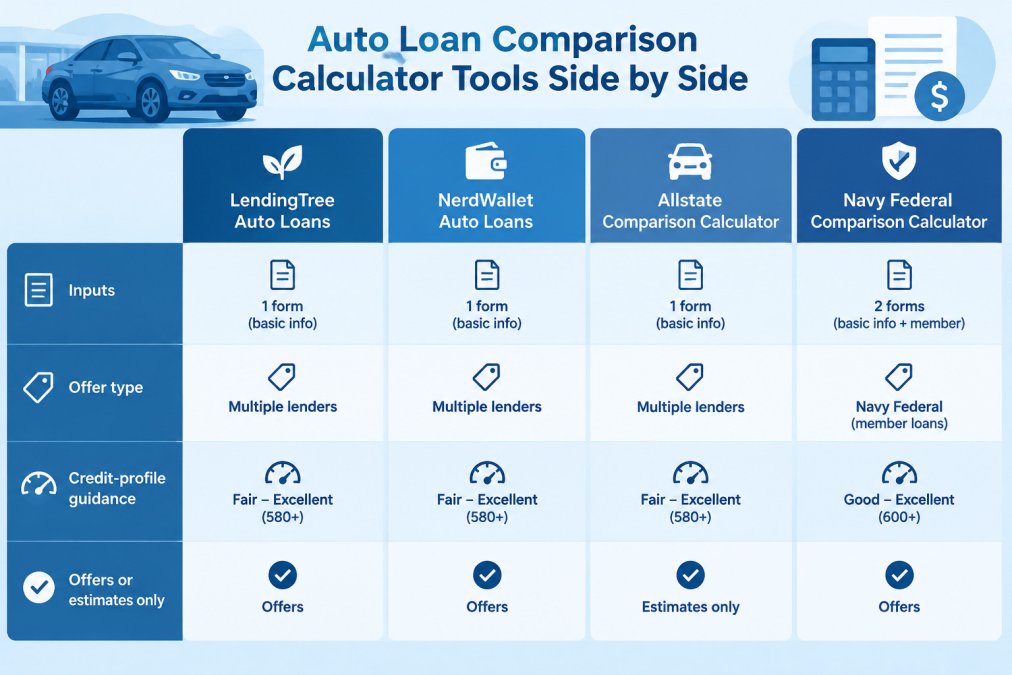
A comparison calculator goes a step further than a single payment calculator. Instead of one loan, it lets you line up several scenarios at once.
Estimate-only calculators. These take a vehicle price, down payment, term and rate you type in, then return a monthly payment and total interest. Some comparison calculators work this way.
Offer-comparison marketplaces. Marketplace-style tools work differently. They route a short application to multiple lenders and may return prequalified offers, which can tie the rate to your credit profile rather than a guess.
| Tool | Main Use | Offers or Estimates | Best For |
|---|---|---|---|
| LendingTree Auto Loans | Compare lender offers | Offers from multiple lenders | Shoppers wanting real offers |
| NerdWallet Auto Loans | Compare lenders by credit profile | Offers and guidance | Borrowers with any credit tier |
| Allstate Comparison Calculator | Compare payment scenarios | Estimates only | Comparing down payment and term |
| Navy Federal Comparison Calculator | Compare rates and terms | Estimates and guidance | Rate-focused calculator users |
!Feature comparison matrix of auto loan calculator tools across inputs, offer type and credit guidance
How to Compare Offers Apples to Apples
Most shoppers compare the wrong numbers. A lower monthly payment on a longer term can cost thousands more in interest, and a lower rate on a smaller loan can still produce a higher total of payments. To compare fairly, hold four inputs constant across every offer: the same vehicle price, the same down payment, the same term, and the same credit assumptions.
A worked example makes the method concrete. Suppose the negotiated vehicle price is $25,000 and you put $5,000 down, so the amount financed is $20,000. Offer A is a 48-month loan at 7% APR; Offer B is a 72-month loan at 6.5% APR.
Watch out: a comparison calculator that only outputs a monthly payment will make the longer, lower-rate loan look like the better deal when it usually is not.
What to Check Before You Trust a Calculator's Output
- Rate source. Does the tool use an advertised rate, a rate you enter, or a rate tied to your credit? Advertised rates are typically reserved for the highest credit tiers.
- Fees included. Many calculators ignore origination, documentation and dealer fees, which inflate the true APR.
- Taxes and add-ons. Sales tax, registration and optional products like gap coverage change the amount financed.
- Privacy. Estimate-only tools usually require no personal data; marketplaces do. Know which one you are using before you enter a Social Security number.
Consumer Financial Protection Bureau auto loan calculator
Affordable Auto Financing Tools for Bad Credit Borrowers
Bad credit does not rule out financing, but it changes the rate you can expect. Lenders price risk, so a lower score usually means a higher APR and sometimes a larger down payment requirement. Tools that show options by credit profile help you set realistic expectations before you apply.
Comparison tools often organize options around good, fair and bad credit, which makes it easier to see where you may fall. Use the estimate as a planning number. Your actual approval depends on the lender's review of your full credit history.
What Lenders Look at Beyond the Credit Score
A credit score is only one input. Lenders also review income, existing debt, employment history and the loan amount relative to the vehicle's value. A larger down payment can offset a weaker score because it reduces the lender's exposure.
Many borrowers focus only on the score and miss these other factors. If you have a recent job change or high monthly debt, address that before you apply.
Total Cost, Loan Terms and Fine Print to Check
The monthly payment is the number most people focus on, but it can hide the real cost. A longer loan term lowers the payment and raises the total interest you pay. It can also leave you owing more than the car is worth for a longer stretch, a condition called negative equity, which becomes a problem if you need to sell or trade the vehicle before the loan is paid off.
The Numbers That Show True Cost
- APR: the yearly cost of borrowing, including certain fees. Compare APR, not the nominal interest rate, because APR folds in some fees.
- Total of payments: every payment added together. This is the figure that shows true cost, and it is the one most shoppers never look at.
- Total interest: the difference between the total of payments and the amount financed.
- Amount financed: the vehicle price minus down payment and trade-in, plus taxes, registration and any add-ons rolled into the loan.
A simple illustration shows why term length matters. On the same amount financed, a 48-month loan at a given APR will carry less total interest than a 72-month loan at the same APR, even though the 72-month payment is lower. The longer term buys a smaller payment with a larger total cost and a longer stretch of negative-equity risk. The right term is the shortest one whose payment still fits your budget with room to spare.
Contract Fine Print Checklist
Before signing, read the contract rather than relying on a tool's estimate. Confirm each of the following:
- Origination or documentation fees. Some lenders charge these upfront or roll them into the loan.
- Prepayment penalty. A fee for paying off early, which some loans charge. Ask directly whether the loan can be paid off early without cost.
- Late fee terms. Know the grace period and the late fee amount.
- Optional products. Gap coverage, extended warranties and credit insurance are often added at signing. Each raises the amount financed and the total cost.
- Simple versus precomputed interest. Simple-interest loans accrue interest daily on the balance; precomputed loans can carry a payoff penalty if you pay early.
Watch out: a dealer add-on rolled into the loan can raise the amount financed enough to push you into a higher loan-to-value tier, which can change the rate you were quoted.
A Budget Worksheet Beyond the Payment Calculator
A payment calculator tells you what the loan costs. It does not tell you what you can afford. Build a monthly car budget that includes the loan payment plus insurance, fuel, maintenance, registration and a reserve for repairs. Keeping total vehicle costs within a comfortable share of take-home pay and leaving an emergency cushion is a common planning approach, because a car budget that consumes every spare dollar leaves nothing for a repair or a missed paycheck. Subtract those costs from your monthly income first, then set your maximum payment, and let that number, not the calculator's output, drive which loan you choose.
Consumer Financial Protection Bureau auto loan shopping worksheet
Best Used Auto Loans and How to Compare Offers
Used-car loans often carry higher rates than new-car loans, and older vehicles may face shorter terms. When you compare offers, line them up on the same basis: same loan amount, same term and the APR, not just the monthly payment.
Compare at least three offers before choosing. Look for the lowest APR, the smallest total of payments and terms that fit your budget without stretching the repayment period too far. A slightly higher payment on a shorter term often costs less overall.
Apply Online and Compare Your Financing Options With Silverton Motors
Once you know your target payment, the next step is to see what you qualify for. You can start your financing application online and see how your numbers compare before you visit the lot. If you are buying in town, get pre-approved for a car in Toms River to know your budget before you shop.
If your credit has been a hurdle, see the step-by-step process for auto financing with bad credit so you know what documents to gather. For terms and approval timing, review how the used car loan approval process works before you sign anything.
Silverton Motors keeps a stock of used cars, trucks and SUVs in inventory. Apply Online to compare your financing options with us, and let us help you find a payment that fits your budget. For current inventory updates and community news, visit our social page.
Frequently Asked Questions
How much car can I afford if I make $70,000 a year?
No single figure fits everyone, because affordability depends on monthly debts, down payment, loan term, insurance costs and the interest rate you qualify for. A common planning approach is to keep total monthly vehicle costs, including the loan payment, insurance and fuel, within a budget you set after covering housing and other obligations. Use an auto loan comparison calculator to test several down payment and term combinations against your actual take-home pay before you shop. Enter realistic insurance estimates, because they can change the total cost meaningfully.
What information do I need to use a car loan calculator?
Most car loan calculators ask for the vehicle price, down payment, trade-in value, loan term in months, and an estimated annual percentage rate (APR). Some also request sales tax and fees, which vary by state, so including them gives a more accurate payment estimate. If you do not know your rate yet, try a few rates across a realistic range to see how sensitive the payment is. The output is an estimate, not a loan offer, so confirm final figures with a lender before you commit.
Can I get a used-car loan with bad credit?
Yes, many lenders offer used-car loans to borrowers with lower credit scores, though the interest rate is typically higher and the approval terms are stricter. Comparison tools that group options by credit profile can help you identify lenders that work with your credit history. Expect to provide proof of income and may be asked for a larger down payment. Compare several offers and look closely at the APR, the loan term and any fees before accepting.
Does a longer auto loan term lower the monthly payment?
A longer loan term spreads the principal over more months, which lowers the monthly payment but usually increases the total interest paid. It can also leave you owing more than the vehicle is worth for a longer period, a situation called negative equity. Use a payment calculator to compare a 36-month and a 60-month term at the same rate and look at the total interest line. The lower payment is only one part of the true cost.